
These days, the news is full of reasons for your nonprofit to build a financial safety net. From government funding cuts to economic uncertainty, many organizations are trying to shore up their finances to prepare for the impacts of these challenges.
This means prioritizing financial sustainability: strategic efforts to build and protect your organization’s finances long-term. We’ll help you get started by covering the following topics:
- What is Financial Sustainability?
- Benefits of Financial Sustainability for Nonprofit Organizations
- Common Roadblocks to Financial Resilience
- Key Components of Financial Sustainability for Nonprofit Organizations
- How to Create a Nonprofit Financial Sustainability Plan
- Free Nonprofit Financial Sustainability Plan Template
Let’s discuss how you can develop a thorough financial sustainability plan that paves the way for long-term financial resilience with the right knowledge, strategies, and support.

What is Nonprofit Financial Sustainability?
Financial sustainability for nonprofit organizations means being able to maintain financial health and mitigate risks long-term. Sustainable organizations have strategic plans to earn, safeguard, and grow their funds so they can do the most good for their missions.
There’s an important distinction to make between financial stability and sustainability:

- Financial stability refers to short-term financial success and self-sufficiency. You might consider your organization to be financially stable now, but what happens when giving suddenly declines or the government pulls its grant funding? Stability means you feel secure in your current financial position, not necessarily your future financial circumstances.
- Financial sustainability involves ongoing, strategic efforts to maintain your nonprofit’s long-term financial health. Sustainability doesn’t stop when your nonprofit is stable and has enough money to operate right now. It entails creating resilient systems that allow your nonprofit to survive and thrive through economic fluctuations, leadership changes, shifting donor priorities, and other challenges.
Stability is important, but you can’t maintain it in the long run without a nonprofit sustainability plan. This plan helps you build a solid foundation for financial resilience now and in the future.
Benefits of Financial Sustainability for Nonprofit Organizations
When your nonprofit is financially sustainable, your organization may be better equipped to:
- Weather economic downturns. Recessions, market fluctuations, and other sudden changes to the economy can decrease donations and increase program costs. When you have a backup plan and funding held in reserve, it’s easier to keep operations running smoothly.
- Face unknown challenges with resiliency. You never know when your organization may face a crisis, whether that’s a natural disaster or a disruptive regulatory change. Clear plans for financial sustainability help you stay prepared for whatever comes your way.
- Further your mission long-term. The better your nonprofit’s financial standing, the more you can do for your mission. By remaining financially sustainable, your staff can devote more time, money, and energy to their work without worrying about losing funding.
- Maintain donors’ trust and faith in your nonprofit. Supporters want to know that you have your nonprofit’s best interests at heart and plan to continue your work for generations to come. Sustainability plans prove that you’re thinking long-term and stewarding funds responsibly.
- Reduce financial management headaches. Managing all your organization’s assets can be overwhelming, especially if you don’t have established protocols and guidelines. Becoming more financially sustainable involves ironing out your management practices, which can lead to better outcomes and less stress for staff members.
Put in the work now to bolster your organization’s financial plans and strategies, and it could pay off for years to come.
Common Roadblocks to Financial Resilience
Today’s organizations face many challenges, and taking extra time to shore up their finances can feel like an additional hassle. This is especially true when they have to make substantial changes to how they operate. We’ve seen nonprofits struggle with roadblocks like:
- Over-dependence on one funding source
- Leadership turnover and lack of succession planning
- Low financial literacy among staff
- No avenue to accept non-traditional large donations (like stocks)
- Difficulty managing multiple bank accounts
- Insufficient FDIC coverage for their reserves
- Limited knowledge of nonprofit investing strategies
- Reserve funds losing value due to inflation
Each of these roadblocks is normal, and our fiduciary advisors have helped nonprofits of all stripes navigate them. We’ll address how you can account for common issues like these in your nonprofit sustainability plan below.
Key Components of Financial Sustainability for Nonprofit Organizations
Now that you understand its importance, let’s break down what financial sustainability actually looks like. Typically, it starts with having the following key components:

Mission and Community Alignment
Before establishing any new financial practices, ensure that your organization’s mission and values are solidified. Aim to align every financial decision with your cause and your community's values. Otherwise, you risk alienating your donor base and losing support.
For instance, say that you start an endowment for your nonprofit. Align the endowment’s investing strategies with your organizational values. You might set a higher annual distribution rate, for example, or specify that donated funds should be invested in line with certain ethical standards.
Diversified Assets
Diversification is the key to attaining financial sustainability for nonprofits. Relying on one source of funding or too many restricted revenue sources can leave your organization vulnerable.
To mitigate these risks, prioritize several different funding opportunities. These might include:
- Recurring giving: Encourage recurring or monthly donations to provide a steady stream of revenue. Cultivate relationships with individual donors through personalized appeals, donor stewardship, and engagement activities.
- Non-cash giving: Expand revenue opportunities by accepting high-impact non-cash gifts like stocks and cryptocurrency. Our recent report showed that non-cash giving has grown 135% over the past decade, presenting a major fundraising opportunity for nonprofits.
- Corporate grants and sponsorships: Seek out corporate sponsors and partners that align with your organization's mission and values. Tap into corporate philanthropy programs, employee giving, and cause-related marketing collaborations.
- Foundation and government grants: Use grant databases to research and apply for grants from private foundations, community foundations, and government agencies. Tailor grant proposals to match funders' priorities and demonstrate the impact of your programs.
- Investment income: Investing your nonprofit’s reserve funds in low-risk, highly liquid holdings is often part of financial stewardship. Give your funding the potential to grow over time while keeping it accessible.
When you have income from several different sources coming in, you’ll likely be in a much better position if one suddenly falls through. Even better if the majority of your funding is unrestricted, as this typically means you can spend these funds in whatever way best serves your organization’s needs.
Healthy Reserve Funds
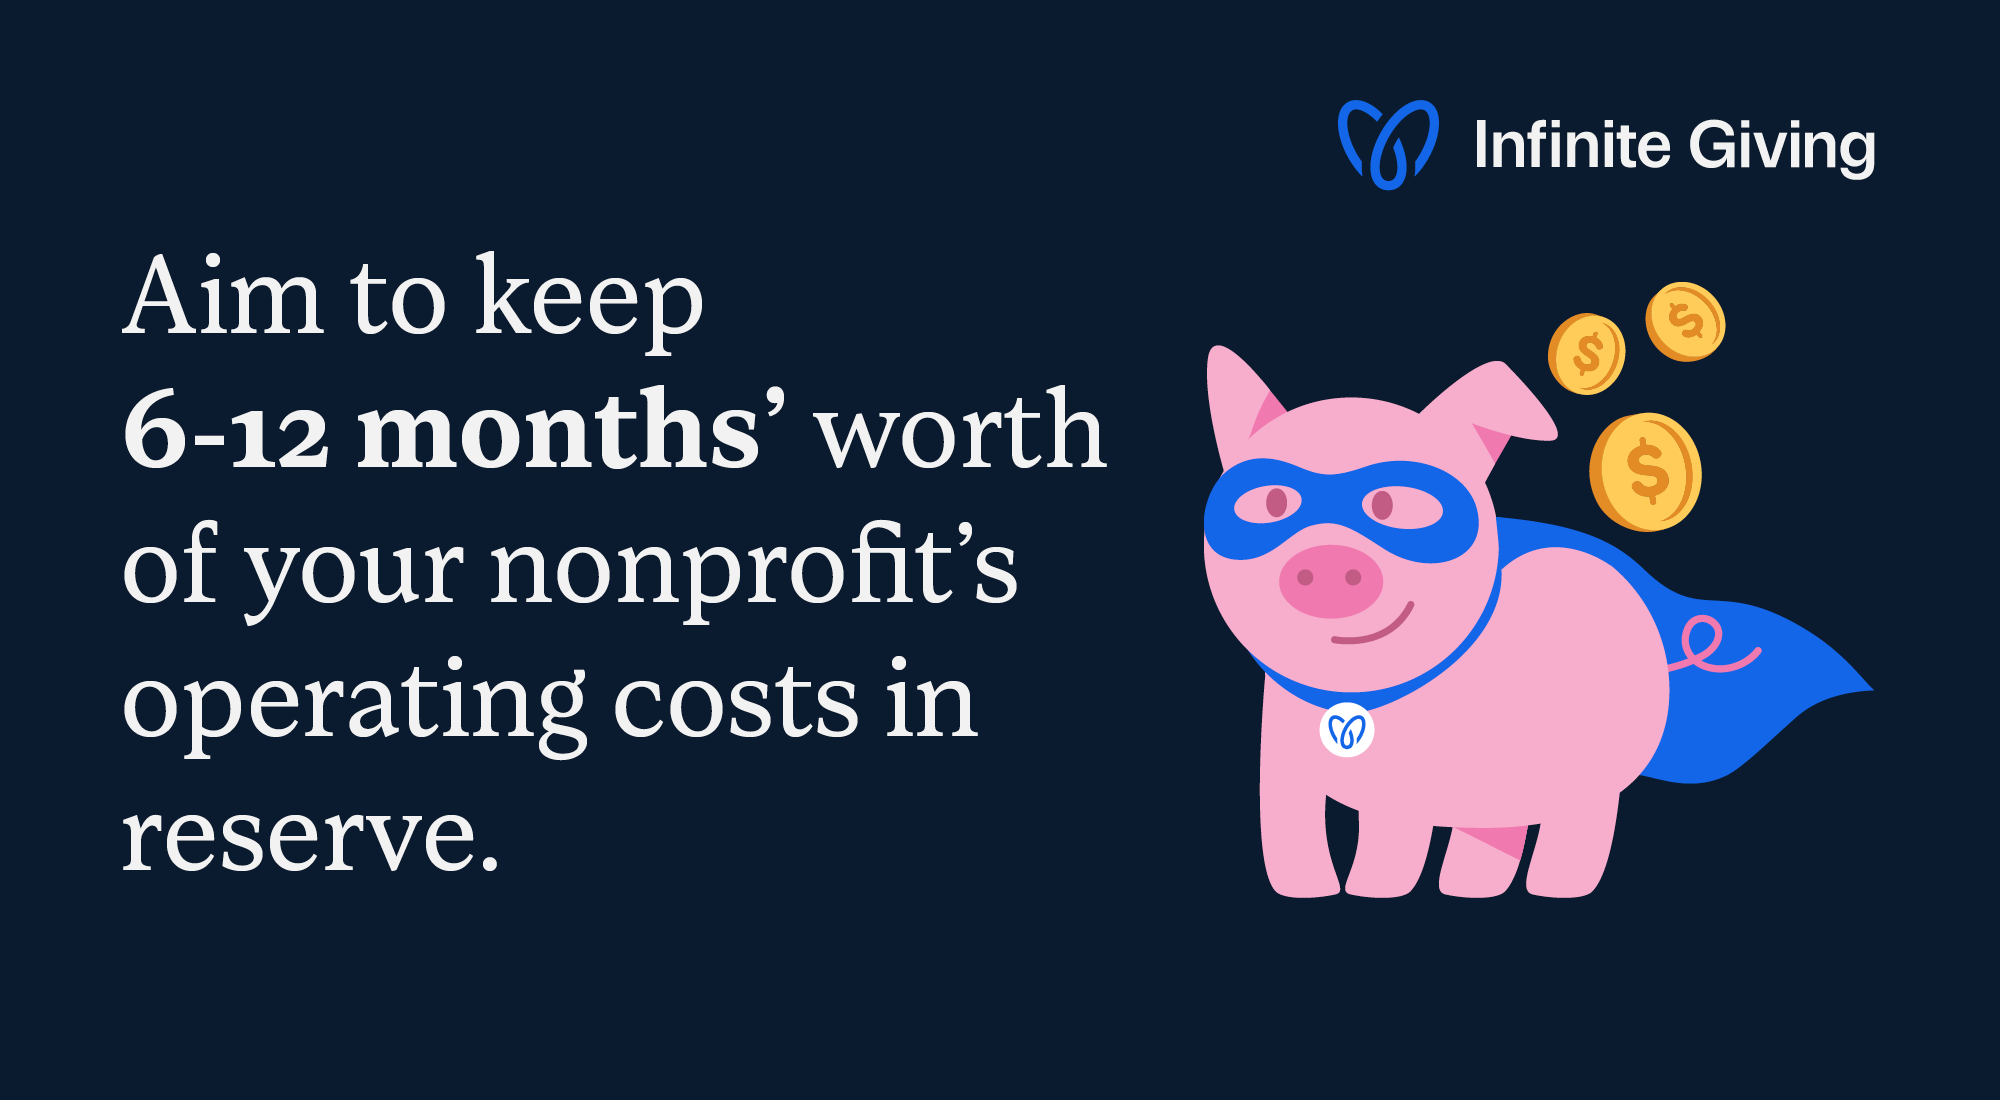
Every organization should have a reserve or rainy day fund. This is an amount of money that you set aside for emergencies, such as losing a large grant or needing urgent repairs to your facilities. Aim to save enough money to cover 6-12 months of your nonprofit’s operating costs.
If you don’t have this much money in reserve yet (or you don’t yet have a reserve fund), don’t worry. Everyone has to start somewhere, and building up reserve funds is a common first priority.
Reserve fund health can also depend on the type of account you store them in. Traditional savings accounts (even high-yield ones) won’t outpace inflation, and you can typically only access FDIC coverage up to $250,000 in a single account. However, brokerage accounts that use a sweep program can increase your coverage up to $5 million. This means that more of your money is backed by the U.S. government, and you can keep everything in one place.
Steward reserves to maintain financial stability and resilience in the face of uncertainty. Establishing and adhering to reserve policies and guidelines can help ensure that reserves are used strategically and sustainably.

Financial Reporting and Oversight
To maintain financial oversight, ensure your board of directors has policies in place to monitor, review, and report on your organization’s financial performance periodically.
For instance, your board may suggest opportunities to generate positive yields on investments and reserves without compromising liquidity or risk tolerance. This may involve diversifying investment portfolios, exploring low-risk investment options, and periodically reviewing investment strategies to adapt to changing market conditions.
Leadership may also establish key performance indicators (KPIs) and metrics to track the effectiveness of your cash management strategies. Use data-driven insights to identify areas for improvement and make informed decisions about resource allocation and investing.
Long-Term Strategic Planning
Consider your goals and vision for your organization’s future. Then, take forward-thinking steps like:
- Budgeting based on revenue forecasts. Develop more realistic budgets that align with your organization's strategic priorities and revenue projections. Monitor actual performance against budgeted targets regularly and make adjustments as needed.
- Creating financial risk management plans. Use scenario planning to predict and address potential risks. Outline detailed plans for how you’ll reduce the likelihood of risks occurring and resolve issues as they arise.
- Developing your staff’s financial planning skills. Invest in professional development opportunities for staff to enhance their skills and knowledge. This not only improves job satisfaction and retention but can also increase organizational capacity and effectiveness.
Often, planning for your nonprofit’s financial future is easier when you have professional support. Consider working with a registered nonprofit investment advisor who can educate you on industry best practices and develop financial sustainability plans that truly serve your organization’s interests and long-term goals.
Ready to create a financial sustainability plan for your nonprofit? Start by following these steps.
1. Assess your current financial situation.
First, get the full picture of your existing finances by evaluating your organization’s annual costs, income, and reserves. Explore the financial data in your CRM, bookkeeping software, and recent reports to ensure your understanding is accurate.
Then, note any information that stands out or needs immediate action. What conclusions can you draw about your current situation? For instance, do you have enough incoming revenue to build a reserve fund? Do you need to identify ways to reduce program costs? Should you hire a full-time bookkeeper to clean up your records?
2. Solidify fundraising plans.
Outline steps to address any issues you identified, then review your annual fundraising plans to see if they align with your financial sustainability goals. Do they involve raising money from diverse revenue streams? Do you have reporting procedures established? Adjust your plans as needed, or add new fundraisers to your calendar to fill in the gaps.
Additionally, consider any technology you may need to better manage and grow your finances long-term. For instance, you might invest in solutions like accounting software, non-cash donation platforms, or productivity tools that streamline operations and improve efficiency.
3. Plan for investment and financial growth.
Your leaders are obligated to act as custodians of your organization's financial resources, ensuring they are protected, optimized, and utilized responsibly. Often, responsible investments are part of a holistic financial stewardship strategy.
Typically, this involves:
- Safeguarding funds in FDIC-insured accounts. Ensure that your funds are deposited at financial institutions that are FDIC-insured. This provides protection against bank failures, keeping your assets secure and accessible when needed.
- Partnering with a nonprofit investment advisor. Professional fiduciaries who specialize in working with nonprofits, like those at Infinite Giving, can manage your portfolios according to your organization’s goals and preferences. They can also recommend opportunities, provide oversight, and support your sustainability journey.
- Prioritizing low-risk, highly liquid strategies. Many nonprofits focus on investments with minimal risk, gradual returns, and high liquidity (meaning you can access funds more quickly when you need them). Often, these strategies can include Treasury bills, mutual funds, and CDARs*.
If you’re looking for professional support, consider the nonprofit financial advisors at Infinite Giving. We offer tailored investment portfolios designed to build financial sustainability for your organization, along with management, fiduciary oversight, regular reporting, and an intuitive platform to provide maximum transparency.
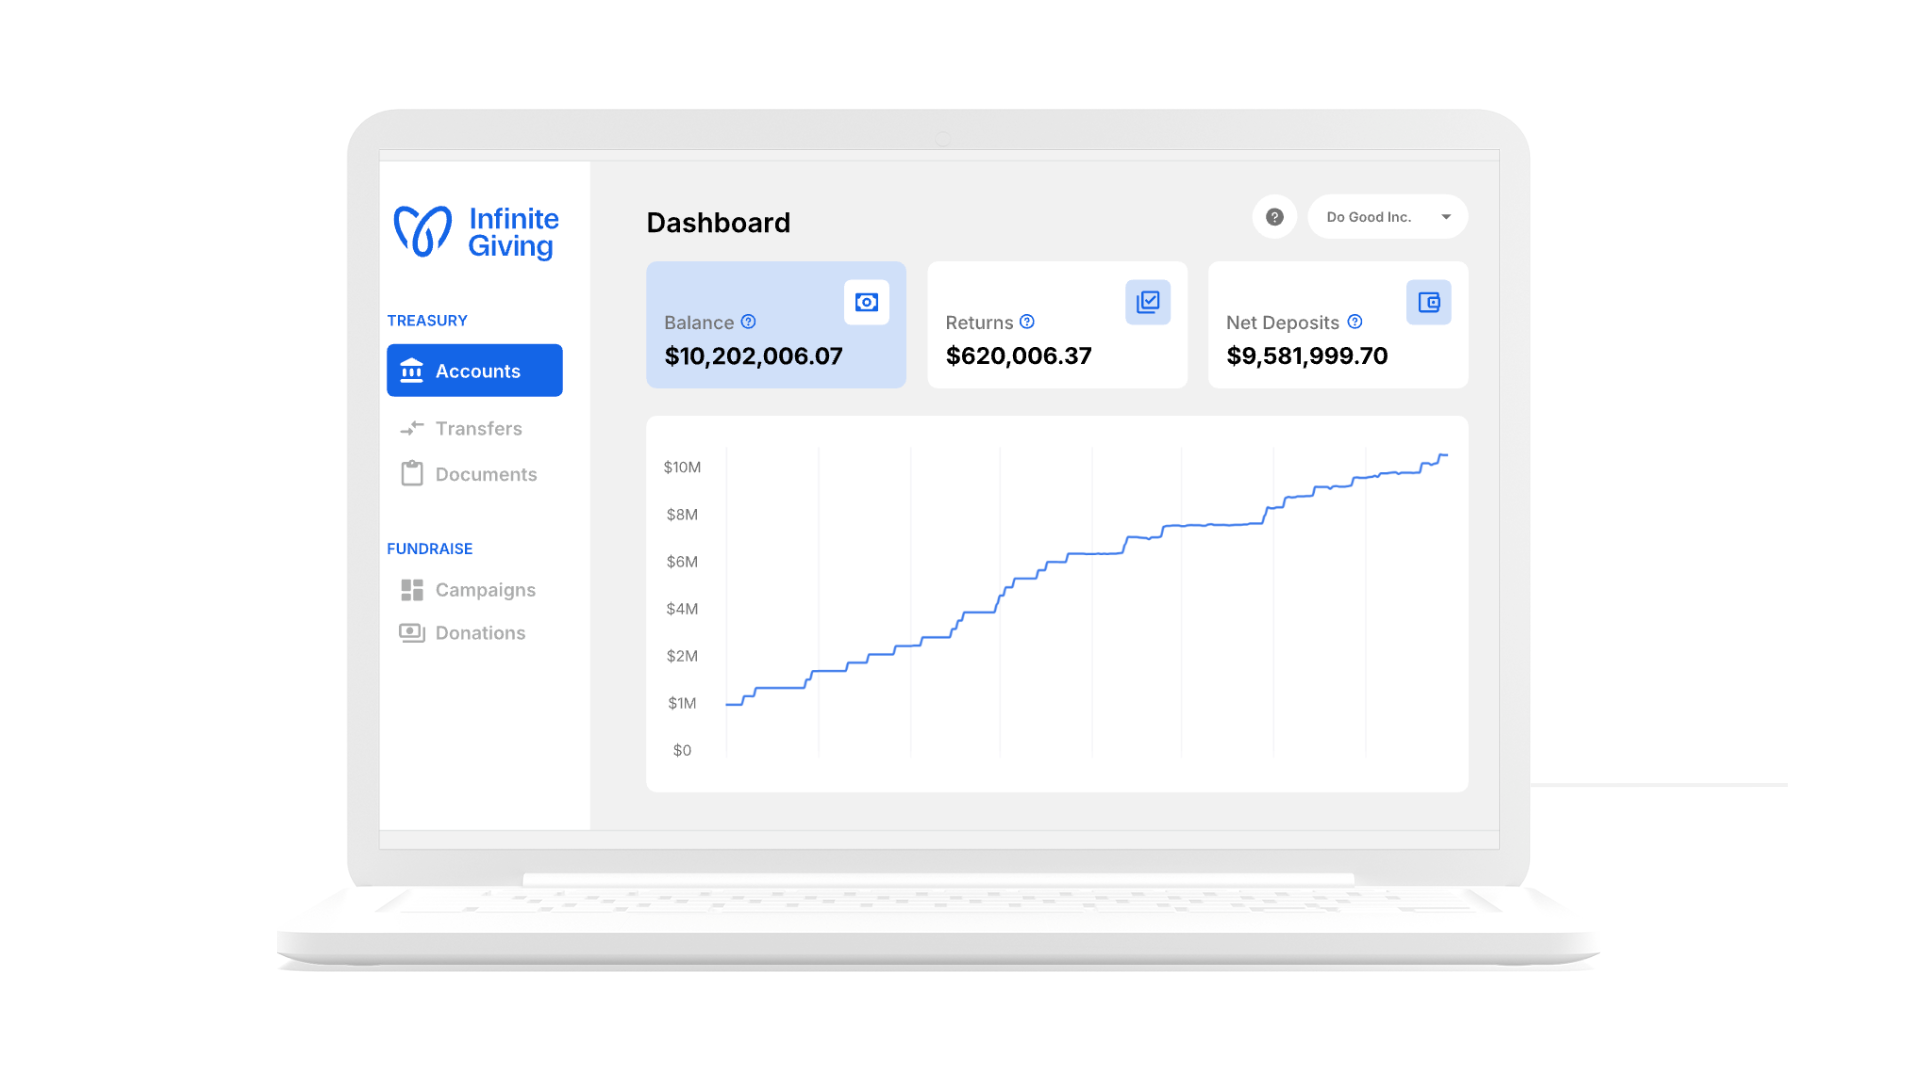
Illustrative example — not actual performance; not indicative of future results.
From your dashboard, you can see updates on your portfolios and endowments at any time. Get an overview of your total returns, net deposits, and earnings.
Plus, we can help diversify your revenue streams with our easy-to-use non-cash donation acceptance tools. In 2025 alone, we processed millions in asset gifts for nonprofits like yours, with an average stock donation of over $32,000. Contact our team to learn how we can help your organization build financial resilience.
4. Align with your team.
With your new plans and strategies in place, update your entire team on the next steps. Get everyone on the same page about the future of your nonprofit’s finances, and update documentation as needed.
For instance, you might add information about financial stewardship to your strategic plan, outline new responsibilities for board members, and make your investment policy accessible for all relevant team members.
5. Report on finances transparently.
Finally, regularly report on your financial standing to key stakeholders like staff, grantmakers, donors, and the wider public. Stay compliant with all IRS reporting requirements, and publicize your reports to show donors that you’re open about your finances. This can help you generate more trust and showcase your organization’s progress towards sustainability.
Free Nonprofit Sustainability Plan Template
Need help keeping track of your sustainability efforts? Use our free nonprofit sustainability plan template to organize your progress with common strategies.
More Resources for Building Nonprofit Financial Resilience
Financial sustainability is a journey, not something you can just check off your list. With strategic planning and a proactive mindset, your nonprofit can strengthen its financial footing and better serve your community for years to come. Use this guide as a starting point to evaluate your own practices and begin shaping a more resilient organization.
Want to learn more about how you can improve your financial practices? Check out these resources from our team:
- Cash Management for Nonprofit Organizations: Basics + 8 Tips. Need a refresher on the basics of responsible financial management? Read this guide and discover the latest best practices for nonprofits.
- Working with Nonprofit Investment Advisors: FAQs and Tips. If you’re wondering what it’s like to work with an investment advisor and whether it’s worthwhile, this guide is for you. Explore FAQs and tips for making the most of the relationship.
- Nonprofit Brokerage Accounts: Guide, FAQ, & How to Open One. A brokerage account is essential for protecting your reserve funds and giving them opportunities to grow. Learn how to open one for your nonprofit here.

Karen Houghton, CEO and Founder of Infinite Giving
Karen Houghton is the CEO and co-founder of Infinite Giving, a Registered Investment Advisor that helps nonprofits build financial sustainability. With a background in both nonprofit leadership and venture capital, Karen brings a rare blend of heart and strategy to financial stewardship. She is passionate about democratizing access to wealth-building tools and guiding mission-driven organizations toward long-term financial health.
As a trusted advisor and advocate, Karen is reshaping how nonprofits think about money as a powerful resource for growing impact. Her work empowers tax-exempt entities to grow their assets, weather uncertainty, and fund their futures.
*DISCLOSURE
Infinite Giving Advisory Services, Inc. is an SEC registered investment adviser. Advisory services are only offered to clients or prospective clients where Infinite Giving Advisory Services, Inc. and its representatives are properly licensed or exempt from licensure. This content is solely for informational purposes. Past performance is no guarantee of future returns.
Investors’ experiences may vary from the content. Nothing in this presentation constitutes investment advice, performance data, or any recommendation that any particular security, portfolio of securities, transaction, or investment strategy is suitable for any specific person. Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Infinite Giving manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary.
Individualized responses to persons that involve either the effecting of transactions in securities, or the rendering of personalized investment advice for compensation, will not be made without registration or exemption. Investing involves risk and possible loss of principal capital. No advice may be rendered by Infinite Giving Advisory Services, Inc. unless a client service agreement is in place. Donation services provided by Infinite Giving Technologies, Inc.
The information, opinions, and views expressed in this material are provided as of the date indicated and are subject to change without notice. No obligation is undertaken to update or revise this material to reflect events or circumstances occurring after the initial publication date.